This post may contain affiliate links. See our disclosure.
Debt Snowball vs. Avalanche: Which One Should You Actually Use?
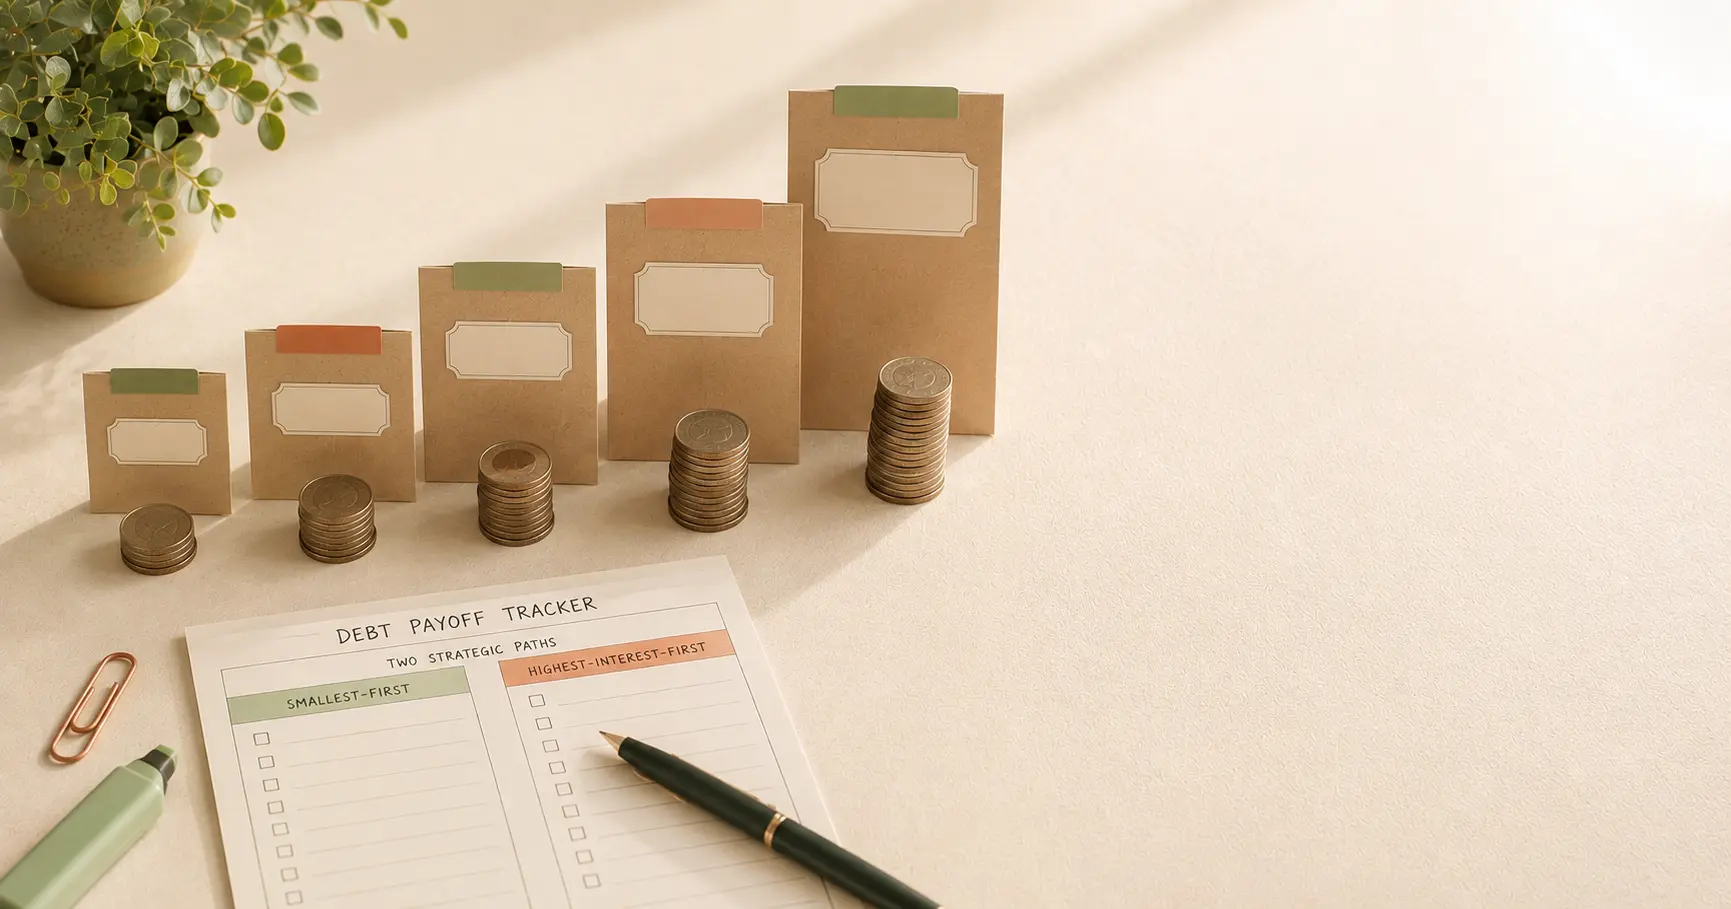
Ask ten people whether you should pay off debt smallest-balance-first or highest-interest-first and you'll get ten confident, contradictory answers. Here's the actual trade-off, in plain numbers, plus a short self-assessment to help you pick without needing a finance degree.
This post contains affiliate links. If you purchase through one, PennyBloom may earn a small commission at no extra cost to you. See our full disclosure for details.
The Two Methods, Defined Simply
Debt Snowball: List your debts from smallest balance to largest, regardless of interest rate. Pay minimums on everything except the smallest, and throw every extra dollar at that one until it's gone. Then roll that entire payment — minimum plus extra — onto the next-smallest debt. Repeat.
Debt Avalanche: List your debts from highest interest rate to lowest, regardless of balance size. Pay minimums on everything except the highest-rate debt, and throw every extra dollar there until it's gone. Then roll that payment onto the next-highest-rate debt. Repeat.
The mechanics are identical — the only difference is which debt you attack first.
The Math: A Real Worked Example
Say you have three debts and $200/month extra to put toward payoff, beyond minimums:
| Debt | Balance | Interest rate | Minimum payment |
|---|---|---|---|
| Credit card | $2,000 | 22% | $60 |
| Personal loan | $5,000 | 11% | $150 |
| Car loan | $9,000 | 5% | $220 |
Snowball order (smallest balance first): Credit card → Personal loan → Car loan Avalanche order (highest rate first): Credit card → Personal loan → Car loan
In this particular case, the orders happen to match — the smallest balance is also the highest-rate debt, so there's no trade-off here at all. This is actually common and worth checking for before assuming you need to choose.
Now change one thing — swap the personal loan and car loan balances:
| Debt | Balance | Interest rate | Minimum payment |
|---|---|---|---|
| Credit card | $2,000 | 22% | $60 |
| Car loan | $5,000 | 5% | $150 |
| Personal loan | $9,000 | 11% | $220 |
Snowball order: Credit card ($2,000) → Car loan ($5,000) → Personal loan ($9,000) Avalanche order: Credit card (22%) → Personal loan (11%) → Car loan (5%)
Here they genuinely diverge. Avalanche tackles the 11% personal loan before the 5% car loan, saving meaningfully more in interest over the payoff period — because more of your money spends less time accruing at the higher rate. Snowball clears the car loan faster (smaller balance), giving you a second "paid off" win sooner, but leaves the 9% higher-rate personal loan accruing interest longer.
The size of the gap between the two methods always comes down to one thing: how spread out your interest rates are. Similar rates across all your debts → the methods perform almost identically, so pick based on motivation alone. Wide spread between rates → avalanche's savings become real money, not just a rounding difference.
Quick Self-Assessment: Which Fits You
Answer honestly — this isn't about which method sounds more responsible, it's about which one you'll actually finish.
-
Have you started and abandoned a debt payoff plan before? If yes, weight toward snowball — quick wins are a real psychological lever, not a consolation prize for people who "can't do math."
-
Is there a wide spread between your highest and lowest interest rates? If yes (say, more than 10 percentage points apart), weight toward avalanche — the dollar savings are large enough to matter.
-
Do you need visible progress to stay motivated month to month? If yes, weight toward snowball, or consider tracking "debts eliminated" as a visible metric even while running avalanche math.
-
Are you disciplined with automated, unglamorous progress (like a retirement contribution you never think about)? If yes, avalanche will probably suit you fine — you don't need the dopamine hit of a fully-paid balance to keep going.
Three or more answers pointing one direction is a reasonably strong signal. A even split means the numeric difference between methods is probably small enough that motivation should be the deciding factor.
The Hybrid Approach
Most comparisons present this as binary, but you're allowed to blend them:
- Snowball-to-avalanche: Use snowball for your first one or two debts to build momentum and prove to yourself the plan is working, then switch to strict avalanche once the habit is established and the psychological need for quick wins has faded.
- Avalanche with a "close-balance" exception: Follow avalanche order, but if two debts have similar rates, pay off the smaller balance first — you get the interest-savings logic of avalanche most of the time, with an occasional quick win when it costs you almost nothing to take it.
- Threshold rule: Some people set a rule like "if a debt is under $500, clear it first regardless of rate" — small balances often carry outsized mental weight relative to the actual interest cost of delaying them.
None of these are "cheating" — the discipline of actually making extra payments matters more than which order you make them in.
Step-by-Step: Setting Up Either Method
- List every debt with balance, interest rate, and minimum payment. This alone takes most people 15-20 minutes and is often the step people skip, which is why they never start.
- Choose your order based on the method (or hybrid) you picked above.
- Confirm minimum payments are covered on everything — neither method works if you're behind on minimums elsewhere; that damages your credit regardless of your payoff strategy.
- Direct every extra dollar to your #1 target debt. Automate this if your bank/lender allows scheduled extra payments, so it doesn't depend on remembering each month.
- When a debt is paid off, roll its full payment (minimum + extra) onto the next debt in line. This is the "snowball"/"avalanche" mechanic — the payment amount grows as debts clear, accelerating the timeline.
- Recheck your list every 3-6 months — rates change (especially on variable-rate cards), and a debt that was your #2 avalanche target might move.
Want the math done for you instead of by hand? Run your numbers through the PennyBloom Budget Calculator first to see how much extra you actually have free each month before committing it to either method.
What Derails People on Both Methods
- Not having minimums fully covered before starting. Extra payments mean nothing if a different account is falling behind.
- New debt added mid-plan. A new balance resets the psychology even if the math barely changes — treat new debt as a signal to revisit your budget, not just your payoff order.
- No emergency fund at all. Without even a small buffer ($500-1,000), a single unexpected expense often gets put right back on the credit card you just paid down, undoing months of progress. The 52-week savings challenge is a low-friction way to build that buffer alongside your payoff plan.
- Choosing based on what "sounds smart" instead of what you'll finish. Avalanche is mathematically optimal, but a mathematically optimal plan you abandon in month four saves you nothing. The best method is the one you complete.
Frequently Asked Questions
Which is better: debt snowball or debt avalanche? Mathematically, avalanche always saves more in interest since it targets your highest-rate debt first. Behaviorally, snowball often wins because paying off a full balance quickly builds motivation. The "better" method is whichever one you'll actually stick with for the full payoff period.
How much more does the avalanche method save compared to the snowball? It depends on how spread out your interest rates are. With similar rates across debts, the difference is small. With a wide spread (say, a 24% credit card next to a 6% auto loan), avalanche can save hundreds to low thousands of dollars over the payoff period, since it clears the most expensive debt first.
Can I switch between the debt snowball and avalanche methods? Yes — there's no rule against it. A common hybrid is starting with snowball for one or two quick wins to build momentum, then switching to avalanche once the habit feels established.
Do I need a debt payoff calculator to use these methods? Not strictly, but it removes the manual math and shows your real payoff date and total interest for each method side by side, which makes the trade-off concrete instead of theoretical.
Keep reading:
- The 50/30/20 Rule for Beginners — find your extra "20%" to put toward whichever method you choose
- The 52-Week Savings Challenge — build an emergency fund alongside your debt payoff so new debt doesn't undo your progress
- How to Cut Your Grocery Bill — free up extra cash from your Needs bucket to throw at debt
Not sure where your paycheck should go?
Try the free 50/30/20 calculatorPennyBloom Team
Sharing practical, judgment-free money tips for real American families.
Get free budgeting tips + printables in your inbox
Join thousands of readers getting practical money tips every week. No spam, ever.
Related reads
The 50/30/20 Rule for Beginners: A Simple Way to Finally Budget
New to budgeting? Here's the 50/30/20 rule explained in plain English, with real dollar examples at three income levels and a free calculator to try it yourself.
8 min read
The 52-Week Savings Challenge: How to Actually Finish It This Year
The classic 52-week savings challenge, the reverse version, and a low-income-friendly variant — plus a free printable chart to track your progress week by week.
7 min read
How to Cut Your Grocery Bill by $200 a Month (Without Coupon-Clipping for Hours)
A realistic, stacked system for cutting your grocery bill by around $200 a month — price tracking, meal planning that actually sticks, and smart pantry stockpiling.
7 min read