This post may contain affiliate links. See our disclosure.
The 52-Week Savings Challenge: How to Actually Finish It This Year
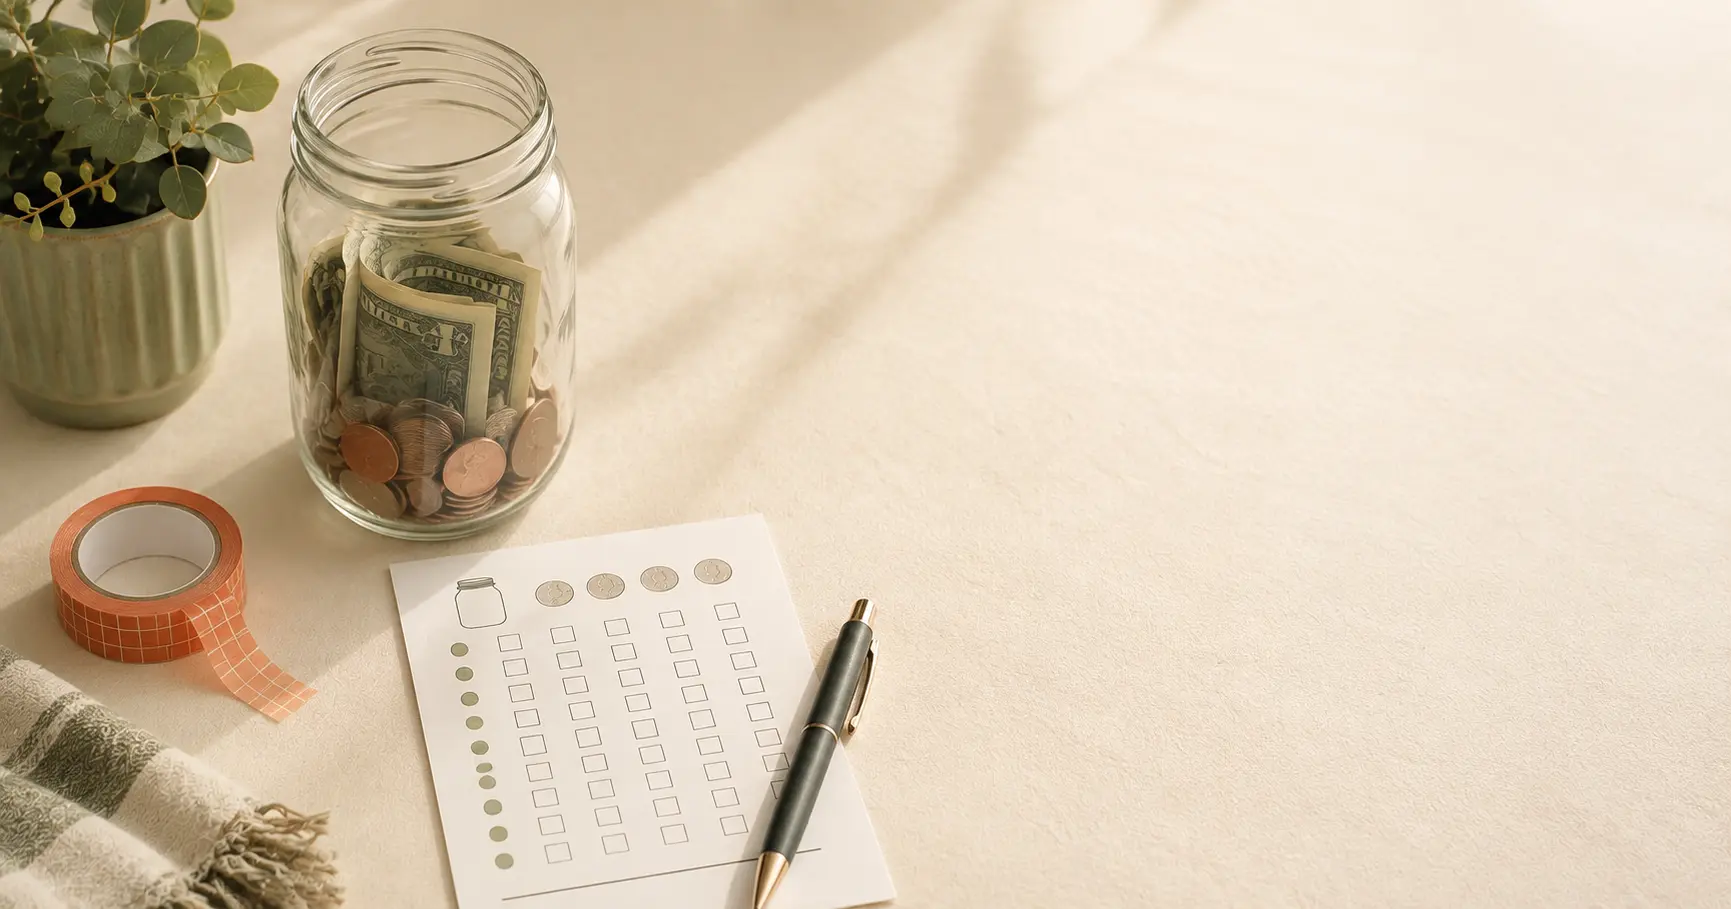
The 52-week savings challenge is one of those ideas that sounds almost too simple to work: save a little more each week for a year, and end up with over a thousand dollars you didn't think you had. It's popular for a reason — it turns saving into a game instead of a grind. The catch is that most people who start it don't finish it. This guide covers the standard version, two variations that are easier to stick with, and a free printable chart to keep yourself on track.
This post contains affiliate links. If you purchase through one, PennyBloom may earn a small commission at no extra cost to you. See our full disclosure for details.
What the 52-Week Challenge Actually Is
The concept is simple: pick a starting amount, then increase your savings deposit by that same amount each week for 52 weeks. The classic version starts at $1:
- Week 1: save $1
- Week 2: save $2
- Week 3: save $3
- ...continuing all the way to Week 52: save $52
Add it all up and you've saved $1,378 over the year — without ever having to find more than $52 in a single week.
Standard vs. Reverse vs. Low-Income Versions
The Standard Version
Best if your income is steady and you expect it to stay that way (or improve) throughout the year. The challenge gets harder as it goes, which mirrors most people's growing comfort with the habit — but it also means the toughest weeks land in November and December, right when holiday spending peaks. That timing mismatch is the #1 reason people quit around week 40.
The Reverse Version
Flip it: start at $52 in week one and count down to $1 in week 52. The math is identical — same $1,378 total — but the big deposits happen early, while motivation (and often income, post-holiday-bonus or post-tax-refund) is highest. By the time you hit the smaller amounts, you're just coasting to the finish line instead of grinding uphill. If you've failed the standard version before, this is usually the fix.
The Low-Income / Flexible Version
If $52 in a single week isn't realistic, scale the increment down rather than abandoning the structure:
| Starting increment | Total after 52 weeks |
|---|---|
| $0.50 | $689 |
| $1.00 | $1,378 |
| $2.00 | $2,756 |
| $5.00 | $6,890 |
You can also stretch it to a biweekly challenge — same increasing pattern, but on a 26-deposit schedule instead of 52, which halves the frequency without losing the built-in psychology of the increasing amounts.
How Much You'll Actually Save (With the Math)
The reason this works even though the amounts feel small is compounding effort, not compounding interest — you're not relying on investment returns, just consistency. Here's the breakdown for the standard $1-increment version:
- First 13 weeks (Q1): $91
- Weeks 14-26 (Q2): $247
- Weeks 27-39 (Q3): $403
- Weeks 40-52 (Q4): $637
- Total: $1,378
Notice how back-loaded it is — over 46% of your total savings happens in the final quarter. That's exactly why the reverse version exists: it moves that heavy lifting to January and February instead of the already-expensive holiday stretch.
If you park the money in a high-yield savings account instead of a jar, you'll pick up some extra interest on top — not huge over just one year, but it's free money for doing something you were already going to do.
Step-by-Step: Starting This Week
- Pick your version. Standard, reverse, or a scaled-down increment — choose based on your income pattern, not what looks most impressive. Not sure how much room your budget has? Run your take-home pay through the 50/30/20 calculator first — your weekly deposit comes out of that 20% savings bucket.
- Open a separate savings account (or use a physical envelope/jar system if you prefer cash). Keeping it separate from your checking account is the single biggest factor in whether people actually finish.
- Set a recurring calendar reminder, not just a New Year's resolution memory. Weekly, same day, same time.
- Print or download the tracking chart and put it somewhere visible — on the fridge, in your planner, wherever you'll actually see it.
- Automate what you can. If your bank allows scheduled transfers, set up an escalating transfer (or the closest approximation your bank supports) so you're not relying on willpower every single week.
Where to Keep the Money
A high-yield savings account (HYSA) at an online bank is the best fit for most people:
- Separate from your everyday spending account, so it's genuinely "out of sight"
- Usually no minimum balance to open
- Earns meaningfully more interest than a traditional brick-and-mortar savings account
- Still liquid — you can access it if a real emergency comes up, unlike locking it in a CD
A physical jar works fine too if you're saving in cash or want a visual/tactile reminder, but you lose the interest and the fraud protection a bank account gives you.
Get the Free Printable Chart
Tracking on paper (or a printable PDF you check off) dramatically increases follow-through compared to just "remembering" your weekly amount. Grab the free PennyBloom 52-Week Challenge chart — enter your email below and we'll send it straight to your inbox, along with the reverse and low-income versions so you can pick the one that fits your year.
Want a version that's already filled in with the math done for you, plus space for notes and a bonus no-spend tracker? The PennyBloom Savings Challenge Pack goes further than the free chart with printable versions for all three variations, a debt-payoff hybrid tracker, and a printable savings goal thermometer.
Tips for Not Quitting by Week 6
Week 6 is historically where most people fall off — the novelty wears off, but the habit isn't automatic yet. A few things that help:
- Batch a few weeks at once if you get behind. Missing week 12 doesn't mean the challenge is over — catch up over the next two weeks instead of restarting from scratch.
- Pair it with something you already do. Transfer money right after payday, not on a random Tuesday you have to remember.
- Tell one other person. Accountability doesn't have to be a whole support group — one friend or family member checking in monthly is often enough.
- Use the reverse version if you're prone to quitting. Front-loading the hard weeks when motivation is highest is a legitimate strategy, not cheating.
Frequently Asked Questions
How much money do you end up with after the 52-week savings challenge? The classic version, where you save $1 in week one and increase by $1 each week, totals $1,378 by week 52. The amount scales with whatever starting increment you choose — starting at $5 instead of $1 gets you to $6,890.
What's the difference between the regular and reverse 52-week challenge? The regular version starts small ($1) and increases weekly, ending on the highest amount. The reverse version starts high and decreases, which is easier during the expensive holiday season since your biggest deposits happen early when motivation is fresh.
Can you do the 52-week challenge on a low income? Yes — scale the increments down. A $0.50 starting increment totals about $689 by week 52, and a biweekly version halves the frequency without losing the habit-building structure. The point is consistency, not the specific dollar amount.
Where should I keep my 52-week challenge money? A separate high-yield savings account works best — it's out of sight from your everyday spending account but still earns interest, and most online banks let you open one with no minimum balance.
Keep reading:
- The 50/30/20 Rule for Beginners — figure out how much room your budget has for a weekly savings challenge
- How to Cut Your Grocery Bill Without a Complicated System — free up extra cash to boost your weekly deposits
Not sure where your paycheck should go?
Try the free 50/30/20 calculatorPennyBloom Team
Sharing practical, judgment-free money tips for real American families.
Get free budgeting tips + printables in your inbox
Join thousands of readers getting practical money tips every week. No spam, ever.
Related reads
The 50/30/20 Rule for Beginners: A Simple Way to Finally Budget
New to budgeting? Here's the 50/30/20 rule explained in plain English, with real dollar examples at three income levels and a free calculator to try it yourself.
8 min read
How to Cut Your Grocery Bill by $200 a Month (Without Coupon-Clipping for Hours)
A realistic, stacked system for cutting your grocery bill by around $200 a month — price tracking, meal planning that actually sticks, and smart pantry stockpiling.
7 min read
Sinking Funds: The Budget Trick That Stops Surprise Bills
What a sinking fund actually is, the categories most households need, and a simple system to start and track yours — so predictable expenses stop feeling like emergencies.
11 min read