This post may contain affiliate links. See our disclosure.
Sinking Funds: The Budget Trick That Stops Surprise Bills
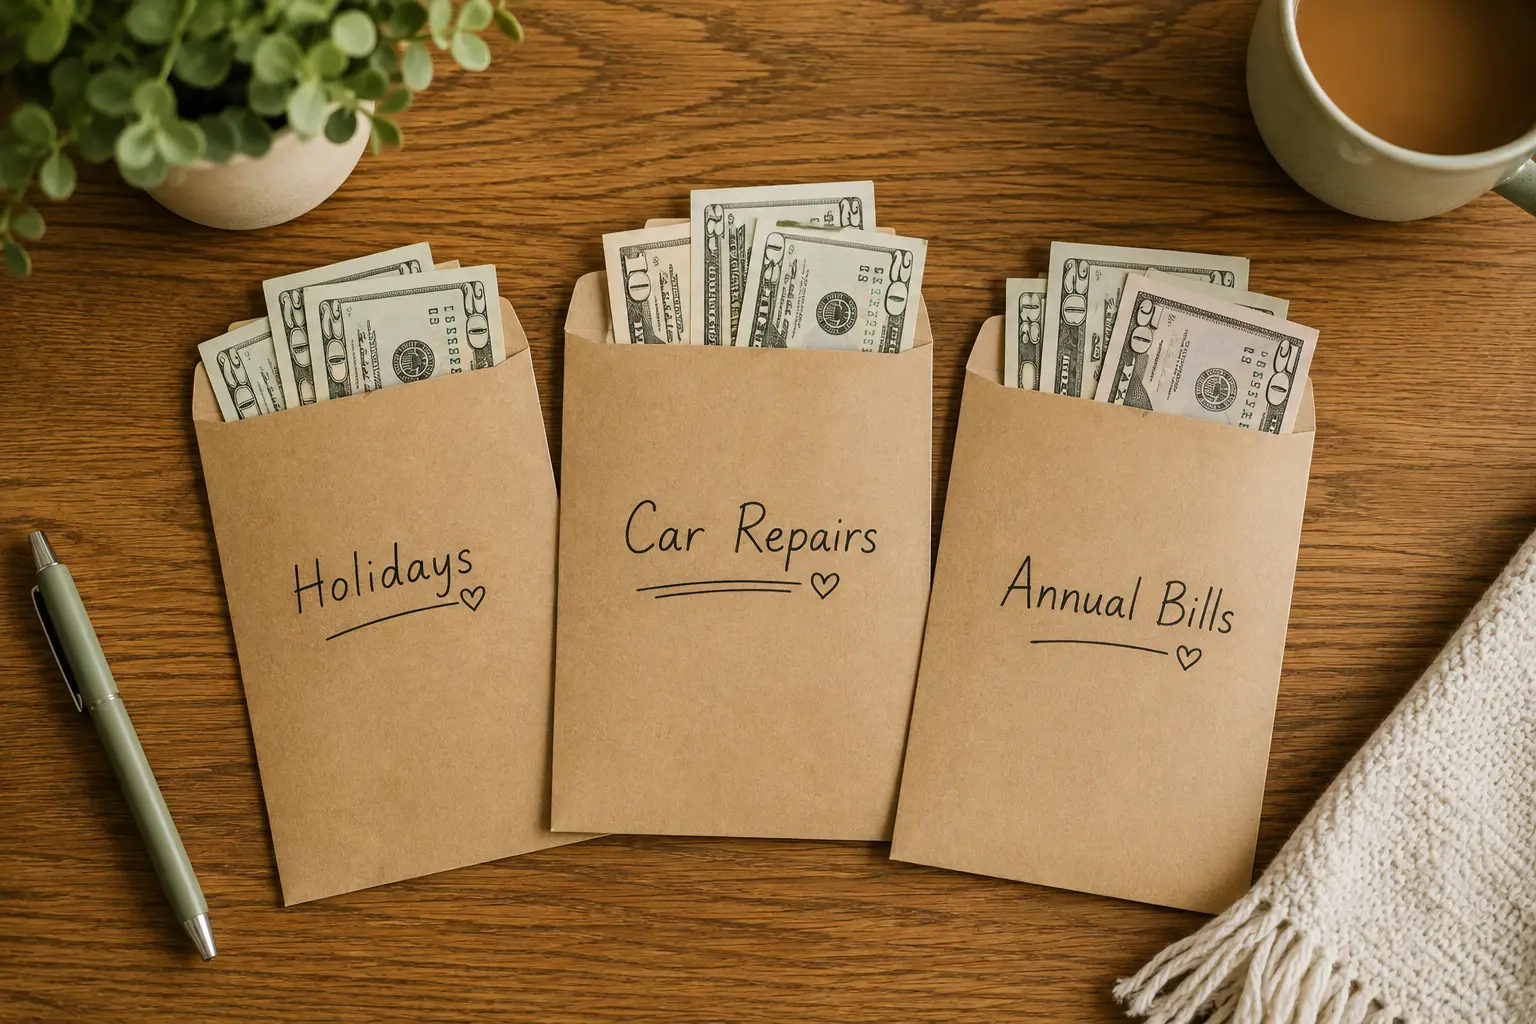
Some of the most stressful bills of the year aren't surprises at all — you know your car will need an oil change, you know the holidays happen every December, you know your car insurance renews every six months. And yet they still manage to land like emergencies, because nothing was set aside for them ahead of time. A sinking fund fixes exactly this gap: it turns a predictable expense into a series of small, boring deposits instead of one uncomfortable lump sum.
This post contains affiliate links. If you purchase through one, PennyBloom may earn a small commission at no extra cost to you. See our full disclosure for details.
What a Sinking Fund Actually Is
A sinking fund is money you set aside gradually, on purpose, for a specific expense you know is coming — just not this week or this month. The math is simple: take the expense's total cost, divide it by the number of months (or weeks) until it's due, and save that amount consistently until it arrives.
For example, if your car insurance premium is $600 and renews every six months, a sinking fund means setting aside $100/month so the $600 is already sitting there, fully funded, the day the bill arrives. No scrambling, no credit card, no "where did that come from" moment.
The concept isn't new — the term originally comes from setting aside money over time to pay off a future debt — but for household budgeting, think of it simply as advance-funding for expenses you can see coming.
Sinking Fund vs. Emergency Fund: Why the Distinction Matters
This is the single most common point of confusion, and getting it right changes how well both systems work.
- Emergency fund: covers the unplanned and unpredictable. A job loss, an unexpected medical bill, a car accident. You genuinely don't know if or when you'll need it.
- Sinking fund: covers the planned and predictable. Holidays, annual premiums, a vacation you're choosing to take, car maintenance you know is coming based on mileage.
Here's why mixing them up causes real problems: if you don't have a holiday sinking fund, December spending often comes straight out of your emergency fund — which then leaves you exposed to an actual emergency in January with a diminished cushion. If your emergency fund keeps getting drained every December, the real fix usually isn't "save more for emergencies" — it's starting a dedicated holiday sinking fund so the two stop competing for the same dollars.
The Sinking Fund Categories Most Households Actually Need
Not every predictable expense needs its own fund from day one. Start with the ones that cause the most budget damage when unfunded:
- Holidays & gifts. Birthdays, holidays, anniversaries — recurring every year, on a predictable calendar, yet somehow still catching people off guard every single time.
- Car maintenance & repairs. Oil changes, tires, brakes, registration renewal. Not "if," but "when" — cars have predictable maintenance schedules even when the exact repair is a surprise.
- Annual & semi-annual bills. Insurance premiums, some subscriptions, professional memberships, property taxes if not escrowed — anything billed less often than monthly gets forgotten between bills.
- Home & appliance maintenance. HVAC servicing, appliance replacement, seasonal home upkeep.
- Medical & dental (planned, non-emergency). Annual deductibles, planned dental work, prescription renewals that come with an out-of-pocket cost.
- Travel. Vacations, trips home for the holidays — funding these in advance means they don't compete with your regular monthly budget when they happen.
Most households get the biggest relief from just the first three. The rest can be added gradually as the system proves itself.
Sample Monthly Sinking Fund Amounts
Numbers make this concrete faster than categories alone. Here's a realistic example for a household budgeting three core categories:
| Category | Annual estimate | Monthly sinking fund amount |
|---|---|---|
| Holidays & gifts | $600 | $50 |
| Car maintenance | $720 | $60 |
| Annual/semi-annual bills | $900 | $75 |
| Total | $2,220/year | $185/month |
$185/month feels like a real number to plan around. $2,220 showing up unplanned across a single year, in unpredictable chunks, is what actually derails most budgets — the sinking fund just spreads the same total cost out into something manageable.
A Worked Example: One Family's Three Sinking Funds
Seeing this run for a full year in one household makes the abstract math feel real. Take a family that decided in January to start three sinking funds at once, funded with a combined $185/month split across the categories above:
- By April (month 4): Car maintenance fund sits at $240 — enough to cover a routine brake job that comes up unexpectedly in May, without touching the emergency fund or a credit card.
- By August (month 8): Holiday fund sits at $400, well ahead of the December rush. They keep contributing the same $50/month straight through the holidays, arriving at the full $600 right on schedule.
- By December (month 12): The annual bills fund has fully covered a $500 car insurance renewal in June and a $400 annual subscription bundle in September, with a small buffer left over heading into next year's estimate.
None of these felt dramatic in any single month — $185 moved automatically, mostly unnoticed. What changed is that three separate bills that used to feel like emergencies simply didn't, because the money was already there, in the right place, before it was needed.
Using Windfalls to Jump-Start a Sinking Fund
Starting a sinking fund from zero in the same month a bill is due obviously doesn't work — the fund needs a head start. Tax refunds, work bonuses, cashback rewards, or a one-time gift are natural ways to front-load a category instead of waiting for 12 months of regular contributions to catch up:
- Use a refund to fully fund one category, then switch to smaller maintenance contributions to keep it topped up going forward.
- Split a bonus across your highest-priority categories rather than putting it all into one, if several are behind where they should be.
- Resist the urge to spend windfalls on non-essentials first. A sinking fund started with a $1,200 tax refund is a full year ahead of one started from a $0 balance in January — that head start is often the difference between a category ever actually getting funded and it staying an idea on a spreadsheet.
How to Start Your First Sinking Fund
- Pick one category to start. Don't launch six sinking funds simultaneously — pick the one that's caused the most budget pain in the last 12 months (for most people, it's holidays or car repairs).
- Estimate the annual cost. Look at last year's actual spending in that category if you can, rather than guessing low.
- Divide by the months until it's needed. A holiday fund started in January has 11-12 months to fill; started in October, it needs a much larger monthly amount to catch up.
- Automate a transfer, even a small one, on the same schedule as your paycheck. Consistency matters more than the amount in any given month.
- Keep it visibly separate from your everyday spending — a labeled sub-account, a separate savings account, or even a clearly marked envelope if you're working in cash.
- Add a second category once the first feels automatic. Layering slowly is far more sustainable than trying to fund everything at once.
Where This Fits in Your Budget
If you're using the 50/30/20 rule, sinking funds live inside your 20% savings & debt bucket, alongside your emergency fund and any extra debt payments. They're not a fourth category — they're a specific use of the savings percentage you're already setting aside.
If your 20% already feels fully claimed by debt payoff or your emergency fund starter goal, that's a sign to look at your Needs and Wants buckets first. A smaller grocery bill freeing up even $50-75/month is often enough to fund your first one or two sinking fund categories without touching anything else in your budget.
Tracking Multiple Sinking Funds Without Losing Your Mind
The moment you have more than one sinking fund running, tracking becomes the make-or-break detail. A few approaches that work:
- Sub-accounts or "buckets." Many online banks let you split one savings account into labeled sub-balances — the money sits in one place, but each category's total stays visible and separate.
- A simple spreadsheet. One row per category, columns for target amount, current balance, and monthly contribution. Update it once a month; it doesn't need to be more sophisticated than that.
- Separate physical envelopes or accounts, if you prefer a fully manual, tactile system. More friction, but some people find that friction is exactly what keeps them from dipping into a category early.
Whatever method you choose, the non-negotiable part is this: you should always be able to answer "how much do I actually have for X?" in under 10 seconds. If you can't, the tracking system is too complicated for daily use, and it'll quietly get abandoned within a few months.
What Happens When a Sinking Fund Runs Short
Sometimes the actual expense comes in higher than estimated, or arrives earlier than planned. This isn't a failure of the system — it's useful information:
- Cover the gap this one time, then increase the monthly contribution going forward so next year's estimate is more accurate.
- Don't abandon the category just because year one wasn't perfectly funded — the alternative (no sinking fund at all) is strictly worse, even with an imperfect estimate.
- Re-check annual estimates yearly. Insurance premiums rise, car maintenance costs shift with the vehicle's age — a sinking fund amount that was right two years ago may need adjusting.
Common Mistakes
- Lumping everything into one general "savings" account. Without category separation, sinking fund money quietly gets spent on whatever feels urgent that week, and the actual targeted expense goes right back to being unfunded when it arrives.
- Underestimating annual costs to make the monthly number feel smaller. A comfortable monthly figure based on an unrealistic annual estimate just recreates the same shortfall you were trying to avoid.
- Starting too many categories at once. Six half-funded sinking funds are less useful than two or three that are actually on track.
- Treating a sinking fund like an emergency fund and dipping into the car maintenance fund for something unrelated — this is exactly the mix-up that undermines both systems at once.
Frequently Asked Questions
What is a sinking fund? A sinking fund is money you set aside gradually, in advance, for an expense you know is coming but that doesn't happen every month — like holiday gifts, an annual insurance premium, or car maintenance. It turns a large, predictable bill into small, manageable weekly or monthly deposits.
What's the difference between a sinking fund and an emergency fund? An emergency fund covers the unplanned and unpredictable — a job loss, a surprise medical bill. A sinking fund covers the planned and predictable — expenses you know are coming, just not this exact week. Mixing the two usually means your "emergency" fund keeps getting drained on things that were never really emergencies.
What sinking fund categories should I start with? Most households benefit most from starting with three: holidays/gifts, car maintenance, and annual or semi-annual bills (insurance premiums, subscriptions, registration fees). Add more categories only once these three are running smoothly.
How do I track multiple sinking funds without it getting complicated? A simple spreadsheet or a banking app that supports sub-accounts (sometimes called "buckets" or "pots") both work well. The key is keeping each category's balance visible separately, even if the money physically sits in one account, so you always know how much is really available for each purpose.
Put Your Numbers to Work
Not sure how much room your budget has for a new sinking fund category? Run your take-home pay through the PennyBloom Budget Calculator to see exactly what's available in your 20% savings bucket before committing to a monthly amount.
Keep reading:
- How to Build an Emergency Fund — the companion system for the expenses you can't see coming
- The 50/30/20 Rule for Beginners — find where sinking funds fit inside your overall budget
- How to Cut Your Grocery Bill — free up the extra cash to fund your first sinking fund category
Not sure where your paycheck should go?
Try the free 50/30/20 calculatorPennyBloom Team
Sharing practical, judgment-free money tips for real American families.
Get free budgeting tips + printables in your inbox
Join thousands of readers getting practical money tips every week. No spam, ever.
Related reads
How to Build an Emergency Fund (When Money's Already Tight)
A realistic, step-by-step guide to starting and growing an emergency fund on any income — even when there's nothing obvious left over each month.
11 min read
The 50/30/20 Rule for Beginners: A Simple Way to Finally Budget
New to budgeting? Here's the 50/30/20 rule explained in plain English, with real dollar examples at three income levels and a free calculator to try it yourself.
8 min read
How to Cut Your Grocery Bill by $200 a Month (Without Coupon-Clipping for Hours)
A realistic, stacked system for cutting your grocery bill by around $200 a month — price tracking, meal planning that actually sticks, and smart pantry stockpiling.
7 min read