This post may contain affiliate links. See our disclosure.
How to Save Money on a Low Income (Starting With $10)
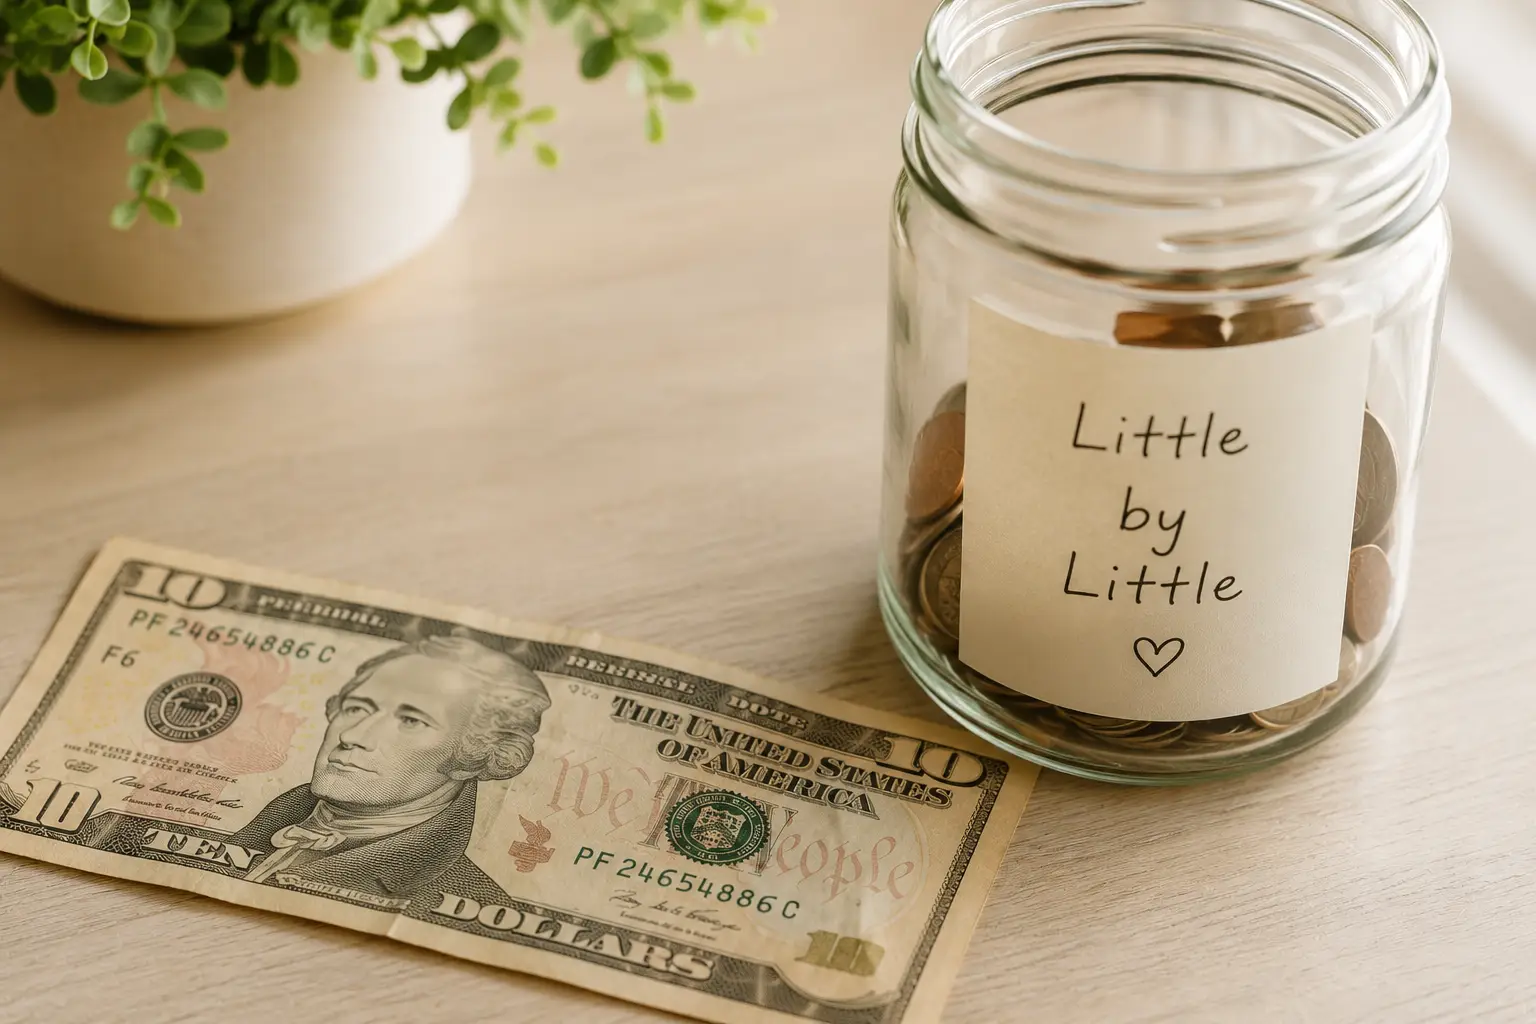
Most saving advice assumes you already have room in your budget somewhere — an unused subscription, a daily coffee, a "want" you can trim. On a genuinely low or tight income, that room often doesn't exist, and advice built for someone with slack in their budget can feel useless at best and condescending at worst. This is a different starting point: real strategies for building a saving habit when the number you're starting with is $10, not $500.
This post contains affiliate links. If you purchase through one, PennyBloom may earn a small commission at no extra cost to you. See our full disclosure for details.
Why Most Saving Advice Fails on a Low Income
A lot of popular saving tips assume a specific kind of household: one with discretionary spending to redirect. "Cancel your subscriptions," "skip the coffee shop," "cook instead of ordering out" — all reasonable for someone who has those expenses in the first place. If your budget is already stripped down to essentials, this advice doesn't just fail to help, it can feel like the problem is being misdiagnosed entirely.
The actual first step isn't finding hidden discretionary spending — for many people at this income level, there isn't any left to find. It's redefining what "saving" means at this stage, so the goal becomes achievable instead of theoretical.
Redefining "Saving" at This Income Level
At a comfortable income, saving usually means setting aside a meaningful percentage — 10%, 20%, whatever a framework like the 50/30/20 rule recommends. At a tight income, that percentage-based thinking can actually work against you, because 20% of very little still feels impossible, and impossible goals get abandoned.
The more useful reframe: saving at this stage is about building a working system, not hitting a percentage. A $5/week habit that actually happens every week is worth more, right now, than a 20% target that never gets attempted because it feels unreachable. The percentage can come later, once the system exists and income changes.
Starting With $10: Why the Number Matters
$10 isn't a token gesture — it's specifically chosen because it's small enough to feel achievable from almost any income, while still being large enough to prove the system works. The goal of your first $10 isn't the $10 itself. It's confirming three things:
- You can identify a real $10 (not a hypothetical one)
- You can move it somewhere separate from your everyday spending
- You can leave it there without touching it
Once those three things are proven at $10, they're the same three things at $20, $50, and $500 — just with more zeros. The hardest part isn't the amount, it's building the proof that the system holds.
Where the First $10 Actually Comes From
Skipping grocery or bill-cutting advice on purpose here — those are worth their own deep dive elsewhere. At this stage, a few other real sources of a first $10:
- Sell one thing you're not using. Clothes, electronics, unused gift cards — a single sold item often covers the entire first deposit in one shot.
- Cash back or rebate apps on purchases you're already making. Not a reason to spend more, but a way to redirect money you're already spending on essentials.
- Round-up savings apps. These round each debit card purchase up to the nearest dollar and save the difference automatically — genuinely invisible money that adds up without requiring a decision each time.
- A single extra hour of gig work or overtime, if that's available to you, earmarked specifically for savings rather than absorbed into regular spending.
- A rebate, reimbursement, or small refund that's about to arrive anyway — redirect it before it lands in your regular spending account.
The point isn't which source you use — it's picking one that's real and available to you specifically, rather than waiting for a "better" moment that may not come.
Automating Micro-Savings
Once the first $10 exists, automation is what keeps the system running without depending on willpower every week:
- Round-up apps (many banking apps now include this natively) — genuinely painless because there's no separate decision to make each time.
- A tiny recurring transfer — even $2-5/week — set up right after payday, before the money has a chance to be absorbed into other spending.
- "Save the change" on cash transactions if you handle physical cash often — a simple jar system works exactly the same way a round-up app does, just manually.
Automation matters more at this income level, not less — when every dollar is being actively tracked and needed, a manual "I'll transfer some at the end of the month" habit almost never survives contact with a tight month.
Building a System With Irregular or Paycheck-to-Paycheck Income
Irregular income (gig work, tips, variable hours) adds a real complication: a fixed weekly savings amount doesn't map cleanly onto income that changes week to week. A more flexible approach:
- Save a percentage of each paycheck instead of a fixed dollar amount — even 2-3% scales naturally with whatever comes in, rather than becoming impossible during a lean week or trivially easy during a good one.
- Use "good week" surplus deliberately. When a bigger paycheck or extra shift comes through, decide in advance what percentage goes to savings before the rest gets absorbed into regular spending.
- Keep a very low floor for lean weeks. Even $1-2 during the tightest weeks keeps the habit alive, which matters more long-term than any single week's amount.
A Realistic First Month, Day by Day
Abstract advice is easier to follow with a concrete picture of how it actually plays out. Here's a plausible first month for someone starting from genuinely nothing:
- Day 1: Open a separate, no-fee savings account online — most take under 10 minutes and require no minimum opening deposit.
- Day 2-3: Identify one item to sell (a drawer of unused cables, an old phone, clothes that no longer fit) and list it.
- Week 1: The item sells for $12. All of it goes straight into the new account — the first deposit, and proof the account isn't just theoretical.
- Week 2: Turn on round-up savings in your banking app if it's available. No decision required going forward — it runs in the background from here on.
- Week 3: A $3 cashback reward from a purchase you were already making gets redirected instead of spent.
- Week 4: Round-ups from the month add up to roughly $6-8, on top of the $12 and $3 already deposited — a first month total somewhere around $21-23, built entirely from money that would otherwise have gone unnoticed.
Twenty-some dollars won't change much on its own. What it proves is the entire point: the system runs, the money stays put, and next month starts from $21 instead of zero.
Growing Past Your First $10: A Realistic Path
Seeing a plausible next few steps makes the whole system feel less like a permanent state and more like a starting point:
| Milestone | Typical approach |
|---|---|
| First $10 | One-time source: sold item, rebate, single extra shift |
| $10 → $50 | Automated $2-5/week transfer, several weeks running |
| $50 → $200 | Round-up app running continuously plus occasional windfalls |
| $200 → $500 (starter emergency fund) | Consistent automated saving plus at least one larger windfall (tax refund, bonus) |
Each stage uses the same underlying system — it just runs longer and compounds. Reaching $500 this way often takes many months, and that timeline is normal, not a sign the system isn't working.
When Saving Feels Genuinely Impossible: A Triage Order
Some months, even $5 isn't realistic, and that's worth naming honestly rather than pretending otherwise. A sane order of priorities when things are that tight:
- Essential bills — housing, utilities, food. These come first, without guilt.
- Minimum payments on any debt. Falling behind here creates larger problems (fees, credit damage) than pausing savings for a month does.
- Even a token savings amount, if truly possible — $1-2, or simply leaving the automated transfer running at its smallest setting rather than canceling it entirely.
If a month requires skipping savings altogether, that's a pause, not a failure — the goal is restarting the next month, not maintaining a perfect streak.
Where to Keep Even a Small Amount
Fees can quietly erase a small balance faster than almost anything else, so account choice matters more here than at higher balances:
- Look specifically for no monthly fee, no minimum balance accounts. Some online banks design accounts specifically for smaller balances without penalty fees.
- Separate from checking, even if it's the same bank — a separate, harder-to-access account meaningfully reduces the chance of spending it on non-emergencies.
- Skip accounts with balance requirements that could trigger a fee if your balance dips below a threshold — at this stage, a fee-free account matters more than a marginally better interest rate.
A Note on Guilt and Comparison
It's worth saying directly: saving $5 a week while a finance influencer talks about maxing out retirement accounts isn't a smaller version of the same effort — it's arguably a harder one, done with less room for error and less margin for mistakes. There's no version of building a savings habit at this income level that deserves less credit than building one with more room to work with. Comparing your specific starting point to advice built for a different starting point is a fast way to feel like you're failing at something you're actually succeeding at. The habit is the achievement here, not the dollar amount next to it.
Common Mistakes
- Waiting for a "real" amount to start. $10 is a real amount. Waiting for $100 or $500 to feel worth starting just delays the system that would have gotten you there.
- Choosing an account with fees that outpace your balance. A monthly fee can erase weeks of small deposits — always check for a genuinely no-fee option.
- Treating a skipped month as a failed system. One paused month doesn't undo previous progress; restarting is the only real requirement.
- Comparing your pace to percentage-based advice that assumes more room in the budget. Your timeline will look different, and that's expected, not a sign of doing it wrong.
Frequently Asked Questions
How can I save money if I'm living paycheck to paycheck? Start smaller than typical advice suggests — $5-10 a week is a real, sustainable starting point, not a token gesture. Automate it right after payday so it happens before the money has a chance to get absorbed elsewhere, and treat the habit as the goal for now, not the dollar amount.
What is micro-saving and does it actually work? Micro-saving means setting aside very small amounts — often through round-ups, tiny automatic transfers, or spare-change apps — consistently over time. It works because it removes the psychological barrier of "I don't have enough to save," and small amounts genuinely compound into meaningful totals over months.
What should I do if there's genuinely nothing left to save each month? Focus on the triage order first: essential bills, then minimum debt payments, then even a token savings amount — even $1-2 a week — to keep the habit and the account itself alive. A savings habit that exists, even tiny, is easier to grow later than one that never started.
Where should I keep money I'm saving on a low income? A no-fee, no-minimum-balance savings account at an online bank works well, since fees can quietly erase small balances. Look specifically for accounts advertised as having zero monthly fees and no minimum balance requirement — some are designed specifically for smaller balances.
See Where Your Money Is Actually Going
Even a tight budget benefits from seeing the numbers laid out plainly. The PennyBloom Budget Calculator breaks your take-home pay into needs, wants, and savings so you can see exactly how much room — even a small amount — genuinely exists.
Keep reading:
- How to Build an Emergency Fund — where your first $500 in micro-savings is headed
- The 52-Week Savings Challenge — a structured way to keep small, growing deposits going
- The 50/30/20 Rule for Beginners — see your full budget picture once the saving habit is running
Not sure where your paycheck should go?
Try the free 50/30/20 calculatorPennyBloom Team
Sharing practical, judgment-free money tips for real American families.
Get free budgeting tips + printables in your inbox
Join thousands of readers getting practical money tips every week. No spam, ever.
Related reads
How to Build an Emergency Fund (When Money's Already Tight)
A realistic, step-by-step guide to starting and growing an emergency fund on any income — even when there's nothing obvious left over each month.
11 min read
The 50/30/20 Rule for Beginners: A Simple Way to Finally Budget
New to budgeting? Here's the 50/30/20 rule explained in plain English, with real dollar examples at three income levels and a free calculator to try it yourself.
8 min read
The 52-Week Savings Challenge: How to Actually Finish It This Year
The classic 52-week savings challenge, the reverse version, and a low-income-friendly variant — plus a free printable chart to track your progress week by week.
7 min read